
Huntington Beach, CA — September 2026
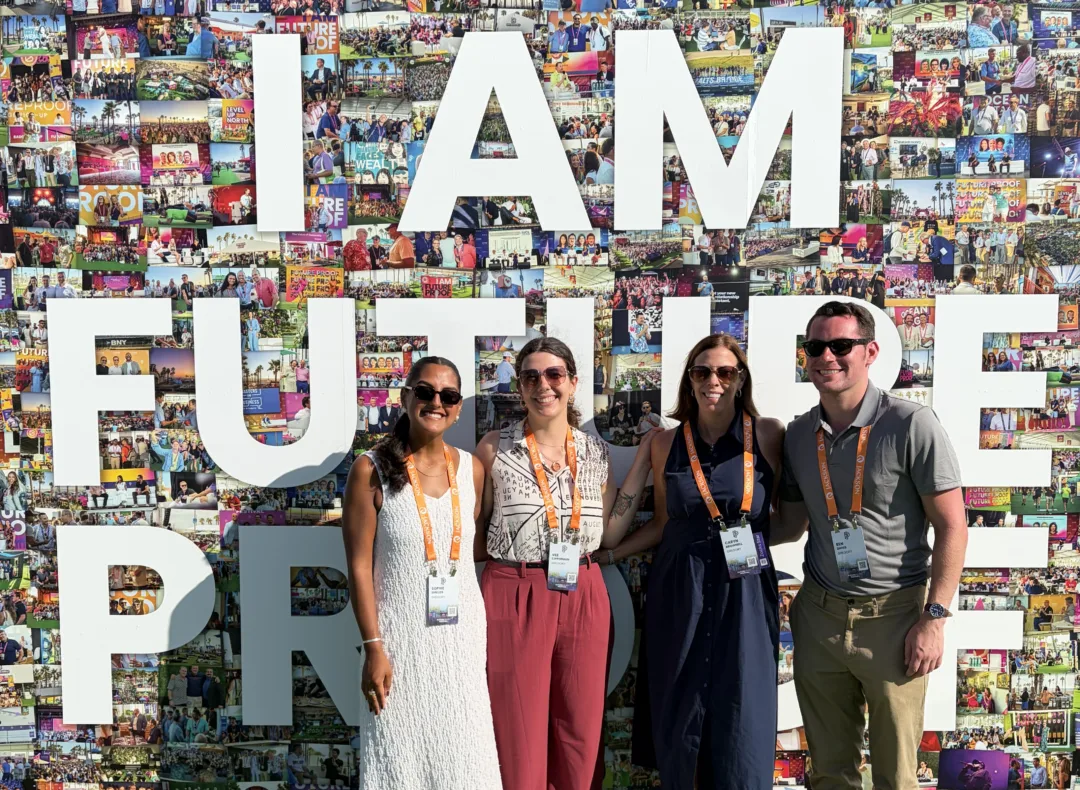
Future Proof Festival doesn't feel like a typical financial services conference, and that's the point. Held entirely outdoors along the beach, its open-air stages and colorful exhibitor tents create a setting that feels more conversational than a traditional industry event.
That format encourages candor that more traditional conferences don't. Across several sessions, from winning next-generation wealth clients and tackling the industry's technology coordination challenges to looking ahead at wealth management in 2030, the same theme kept surfacing: artificial intelligence is rapidly becoming the price of admission, not the differentiator.
The firms that stand apart over the next five years will be the ones building something AI can't manufacture on its own: proprietary data and genuine client trust. Here are the takeaways that stood out most.
"Table stakes" is how the industry talks about AI.
In a discussion about where wealth management is headed by 2030, panelists were direct about how quickly expectations are changing. Tax management, once considered a premium offering, is becoming standard for advisors across the board.
Client expectations for tax planning, personalization, and integrated service move in one direction: up. AI makes it easier for firms to deliver capabilities clients increasingly assume are standard.
The more interesting question is what they build on top of their AI stack that competitors can't easily copy.
AI is only as good as the data underneath it, and most firms don't own theirs.
One conversation offered a clear explanation for why AI hype and AI results look so different in practice. A typical advisory firm runs eight to twelve platforms, each with its own data structure, naming conventions, and billing logic. Advisors have effectively become the integration layer, a role they were never equipped to play.
The core argument was simple: AI is only as effective as the data it sits on top of. For advisory firms, building a universal data environment is becoming a priority, not a nice-to-have.
A parallel idea surfaced in a separate discussion about asset management. Firms generating proprietary data through direct client relationships hold an asset that deserves to be treated as such, not as a byproduct of doing business.
Different conversations, same conclusion: proprietary data is becoming a critical infrastructure layer, and it's one thing a competitor cannot simply copy.
Winning the next generation of clients starts long before there's money to manage.
In a discussion about attracting younger wealth clients, panelists challenged the assumption that younger investors primarily want to manage their finances on their own. The conversation instead centered on demand for real financial advice and for someone who can filter an increasingly overwhelming amount of information.
The sharpest point centered on family transitions. Firms that proactively bring clients' adult children into the relationship, rather than waiting for an inheritance to trigger the first conversation, build trust well before assets change hands.
Trust compounds over time. It cannot be manufactured quickly when the money actually moves.
Earned media's value is the multiplier effect.
The conversation around younger investors also addressed whether earned media still matters, and the answer from panelists was clear: traditional and social media are complementary channels, not competing ones.
Younger clients want access to the same market insight available to high-net-worth investors, and credible media coverage delivers it. A single media hit rarely generates immediate inbound interest on its own. Its value comes from being part of a larger, sustained program that builds visibility, credibility, and search presence, particularly as AI-powered search increasingly shapes how people discover and evaluate firms.
There is also a multiplier effect. One piece of earned coverage becomes a blog post, several social videos, and a series of standalone posts. Third-party validation becomes owned content that keeps working long after the original interview.
Panelists were skeptical of industry rankings and "best of" lists, noting that prospective clients care more about substantive indicators of trust, including a firm's compliance record. Earned coverage builds credibility when it feels like authentic communication rather than self-promotion.
Consolidation and cybersecurity are becoming part of the AI conversation.
Cybersecurity received less attention than AI itself, but it was one of the more consequential themes raised. One panelist shared a candid account of a social-engineering breach at their own firm, warning that AI tools connected to systems such as Salesforce give an intruder access to far more information than a paper file ever could.
Another panelist emphasized that the cybersecurity threat is already here, not something the industry needs to start worrying about four or five years from now.
The conversation also connected cybersecurity to consolidation. As the cost and complexity of protecting client data rise alongside AI adoption, smaller firms face growing pressure to partner with or consolidate into larger organizations with more resources.
Handing work to AI isn't the same as understanding it
Another topic of conversation at the event was the difference between outsourcing and offloading. Outsourcing means understanding a task well enough to hand it off and check the work, while offloading means handing something to AI when you don't understand it yourself and hoping it comes out right.
A firm using AI to speed up something its people already know how to do is in a very different position from one using it to cover a gap in its own expertise. The risk is that no one is equipped to recognize when the output is wrong.
One scenario that raised particular concern was AI-generated work going directly to a client without anyone reviewing it first. AI is going to get things wrong at times, but the bigger problem is allowing those mistakes to reach a client when someone at the firm could have caught them.
As firms bring AI into more parts of their business, they need to know when they're actually outsourcing work and when they're simply offloading it.
The common thread
Across sessions focused on very different parts of wealth management, the same idea kept coming through. AI adoption is no longer much of a differentiator. It is rapidly becoming the entry fee.
What separates firms over the next decade will be what they do with the things AI can't replicate: data no one else has and trust that took years to build. The technology will keep getting better. The edge will not come from the tools themselves. It will come from what firms do with them.